Sebi may review brokers' concerns over MDR on large UPI fund transfers
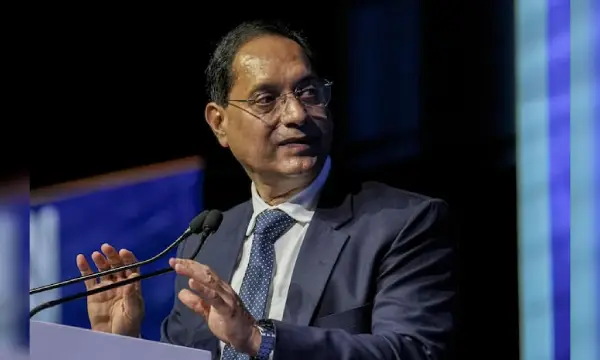
The Securities and Exchange Board of India (Sebi) may look into the issues raised by stock brokers over the new merchant discount rate (MDR) for large fund transfers via the unified payments interface (UPI), Chairman Tuhin Kanta Pandey said on Thursday.
The MDR for capital market transactions has been set at 0.02 per cent of the transaction value, with a maximum cap of Rs 300, for payments towards mutual funds, securities, stock brokers, dealers and investment advisers. The changes will come into effect from October 15.
However, recurring standing instructions or UPI mandates, such as those for mutual fund SIPs, will not carry MDR charges.
“I think there are some important issues there. We will certainly look into it and see how we can ease them,” Pandey said on the sidelines of the National Bank for Financing Infrastructure and Development's Infrastructure Conclave.
Several brokers had raised concerns over the charges as, under the mandate by Sebi, brokers need to return funds to clients periodically — known as the client float. The norm to transfer back unused funds was introduced by Sebi to prevent any misuse of the client float.
“Regulation essentially forces this movement of money every month or quarter, and the broker could end up bearing the cost when the money comes back, without any incremental benefit or revenue,” Nithin Kamath, founder of discount broking platform Zerodha, wrote in a post on his social media handle.
Several other brokers also highlighted that the charge would become a recurring operating cost running into crores, without generating any trade or revenue for the broker.
Payment processing partners of such brokers indicate that some brokers may prefer net banking over UPI, considering that net banking transactions have a flat fee of around Rs 8 to Rs 12, negotiated between banks and payment processing partners.
Speaking at the conference, the Sebi chairman also said the regulator would focus on widening participation in real estate investment trusts (REITs) and infrastructure investment trusts (InvITs), deepening the corporate bond market and continuing to evolve the alternative investment fund (AIF) framework.
He said there was scope to bring more domestic institutional capital, global long-term investors and retail participation into REITs and InvITs, while the corporate bond market needed a wider issuer base, greater participation and better secondary-market liquidity.
Other Latest News
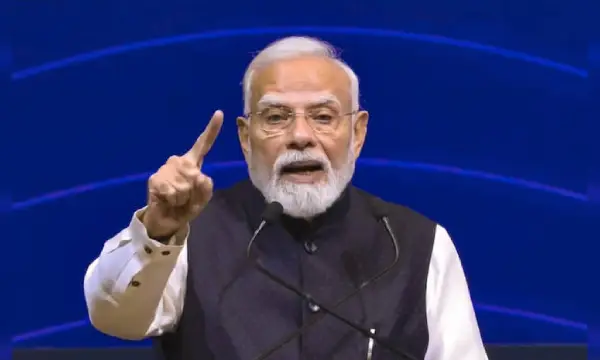
Prime Minister Narendra Modi on Thursday pitched India as a trusted destination for global chip manufacturing and said the government is taking all measures to ensure the industry's success through enabling policies and frameworks.
Speaking at the inauguration of the SEMICON India 2026, the PM said that the semiconductor ecosystem is expanding rapidly, opening new opportunities for innovation, investment and growth.
Tata Electronics will be signing 16 agreements at the SEMICON India conference with players across Europe, Japan, Singapore, and India, CEO Randhir Thakur said on Thursday, adding that the company's 'fab' in Dholera, Gujarat and the packaging facility in Assam are "on track" to meet scheduled commitments made to the government.
The US House of Representatives passed a bill that would authorise President Donald Trump to impose sanctions on Russia and steep tariffs on its trading partners in oil and gas, including India and China.
The Lindsey O Graham Sanctioning Russia and Iran Act of 2026, passed by the US Senate last month, was approved by the House in a 262-159 vote on Wednesday evening and will now go to Trump to be signed into a law.
Telangana has been the country's most inflation-hit state in every single month of the year, an unbroken run at number one from January through August, an analysis of data released by the National Statistics Office (NSO) showed. Its rate climbed steadily through the first half — from 4.92 per cent in January to a peak of 6.36 per cent in June — before easing only fractionally to 6.27 per cent in August.
Digital payments platforms like Paytm and Mobikwik saw a sharp rally of up to 7 per cent in intraday deals on Wednesday, as the introduction of a merchant discount rate (MDR) on UPI transactions is seen as making the payment business structurally self-sustaining and resilient.
Paytm shares rallied 7 per cent to a fresh 52-week high of ₹1,856.50 on the BSE. Mobikwik stock rose by 6 per cent to ₹214. However, Pine Labs slumped 6 per cent to ₹182 per share.